Insurance
We speak adjuster.
We can’t tell you what your policy covers. We can make the claim easier to approve by documenting it properly.
How claims work
Who does what
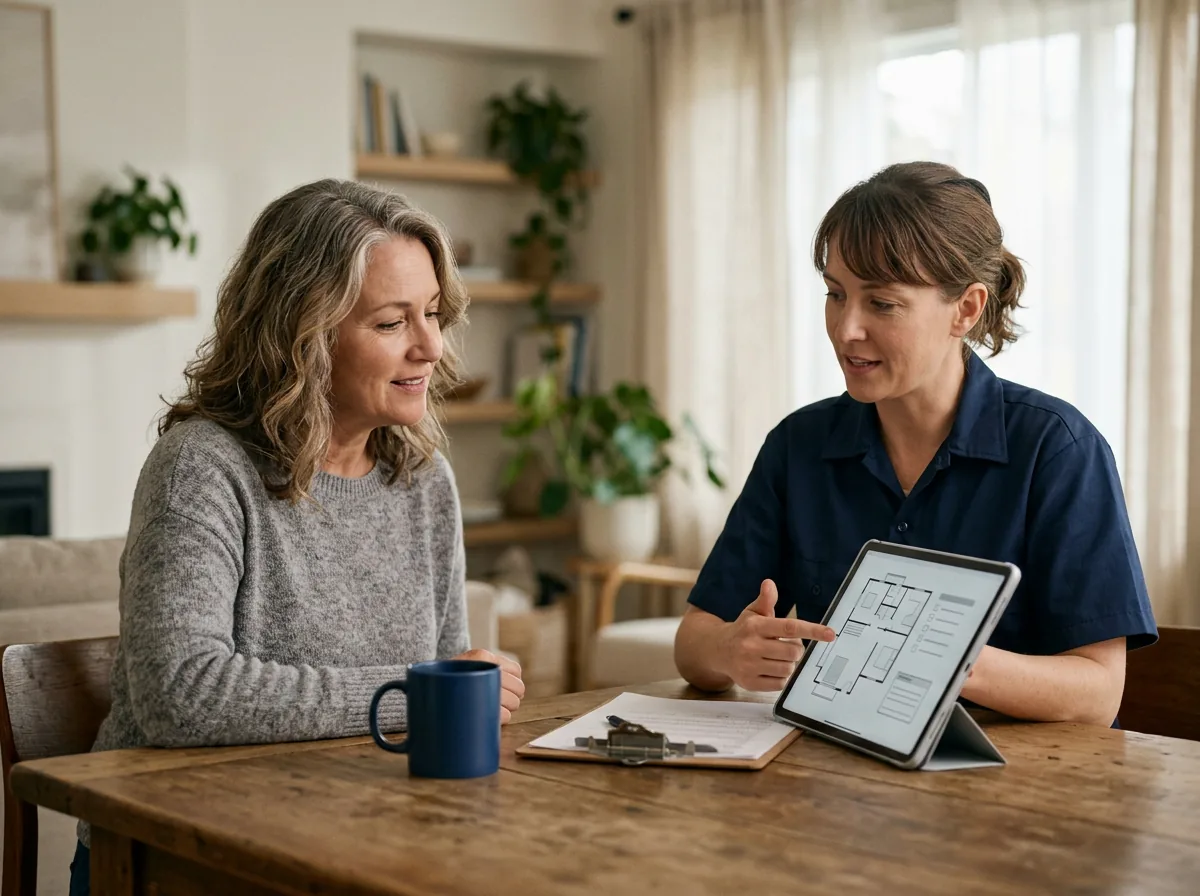
You report the loss to your insurer. Your insurer assigns an adjuster. We document the damage, agree the scope with the adjuster and do the work. You pay your deductible; your policy sets the rest.
You: report the claim and choose your contractor.
Your insurer: decides coverage and payment.
Us: document, estimate, restore and rebuild.
What we provide
The paperwork a claim runs on
01
Photos and video
Before, during and after, time-stamped.
02
Moisture and drying logs
Daily readings that show the work was needed and finished.
03
Itemized estimates
In the estimating format most insurers use: [ESTIMATING SOFTWARE].
04
Direct contact
We talk to your adjuster so you don’t have to relay messages.
Plain note
Coverage, deductibles and payment are between you and your insurer. Nothing on this page is insurance or legal advice. [LOCAL RULES ON CONTRACTOR CHOICE AND ASSIGNMENT OF BENEFITS]
Good to know
Common questions
Will my insurance cover this?
It depends on your policy and the cause. We document the damage and work with your adjuster, but your insurer decides coverage.
Do I have to use the company my insurer suggests?
[LOCAL RULES ON CONTRACTOR CHOICE]. In most cases the choice is yours. Ask your insurer, and call us if you want a second opinion on the scope.
What if my claim is denied?
Ask your insurer for the reason in writing. Our moisture logs, photos and estimates are yours to use if you appeal, and we can explain what we found. We can’t give legal advice.
Do you bill my insurer directly?
[DIRECT BILLING POLICY]. Either way, your project manager sends documentation in the format your adjuster uses.
Damage doesn’t wait. Neither do we.
Call any time. A project manager answers and a crew is sent straight away.